What evidence is needed to pass a carbon reporting audit?
A carbon reporting audit is passed with evidence that lets an independent reviewer trace every reported emissions figure back to a real activity, source document, calculation method, and approved control. A polished emissions dashboard is not enough. Auditors need to see how the number was created, who checked it, what changed during the reporting period, and whether the same process would produce a reliable result again.
The most useful way to prepare is to treat the audit as an evidence chain. For each material emissions figure, the chain should answer five questions:
- What activity created the emissions?
- Where did the underlying data come from?
- Which calculation method and emissions factor were applied?
- Who reviewed or approved the result?
- Can the figure be reproduced from the retained records?
If any link is missing, the issue is usually not the size of the emissions number. It is the inability to demonstrate that the number is complete, consistent, and supportable.
Start with the reporting boundary
Before reviewing invoices, meter readings, or supplier files, an auditor will need to understand what the report covers. This is the reporting boundary: the legal entities, sites, facilities, vehicles, products, and emissions categories included in the carbon inventory.
Evidence for the boundary commonly includes an organization chart, legal-entity list, site register, lease information, operational-control documentation, and a written statement explaining the consolidation approach used. The purpose is to prevent an organization from reporting emissions for selected facilities while unintentionally excluding another location under the same operational control.
This becomes more complicated in cross-border supply chains. A manufacturing group may purchase electricity in one country, operate warehouses in another, and use contract manufacturers elsewhere. The reporting team needs a clear rule for deciding which operations belong in the inventory and which supplier activities are reported as value-chain emissions. A list of sites alone does not prove that the boundary is complete; it must be reconciled to the organization’s actual operating footprint.
Material changes also need an explanation. Acquisitions, site closures, new production lines, changes in leased assets, or a revised ownership structure can all affect comparability. Keep a boundary-change log that states what changed, when it changed, and how the reporting treatment was determined.
Primary activity data is the strongest audit evidence
Auditors generally prefer source records over estimates because source records show the activity that generated emissions. For direct fuel use and purchased energy, the most persuasive evidence is usually the original document created during normal operations.
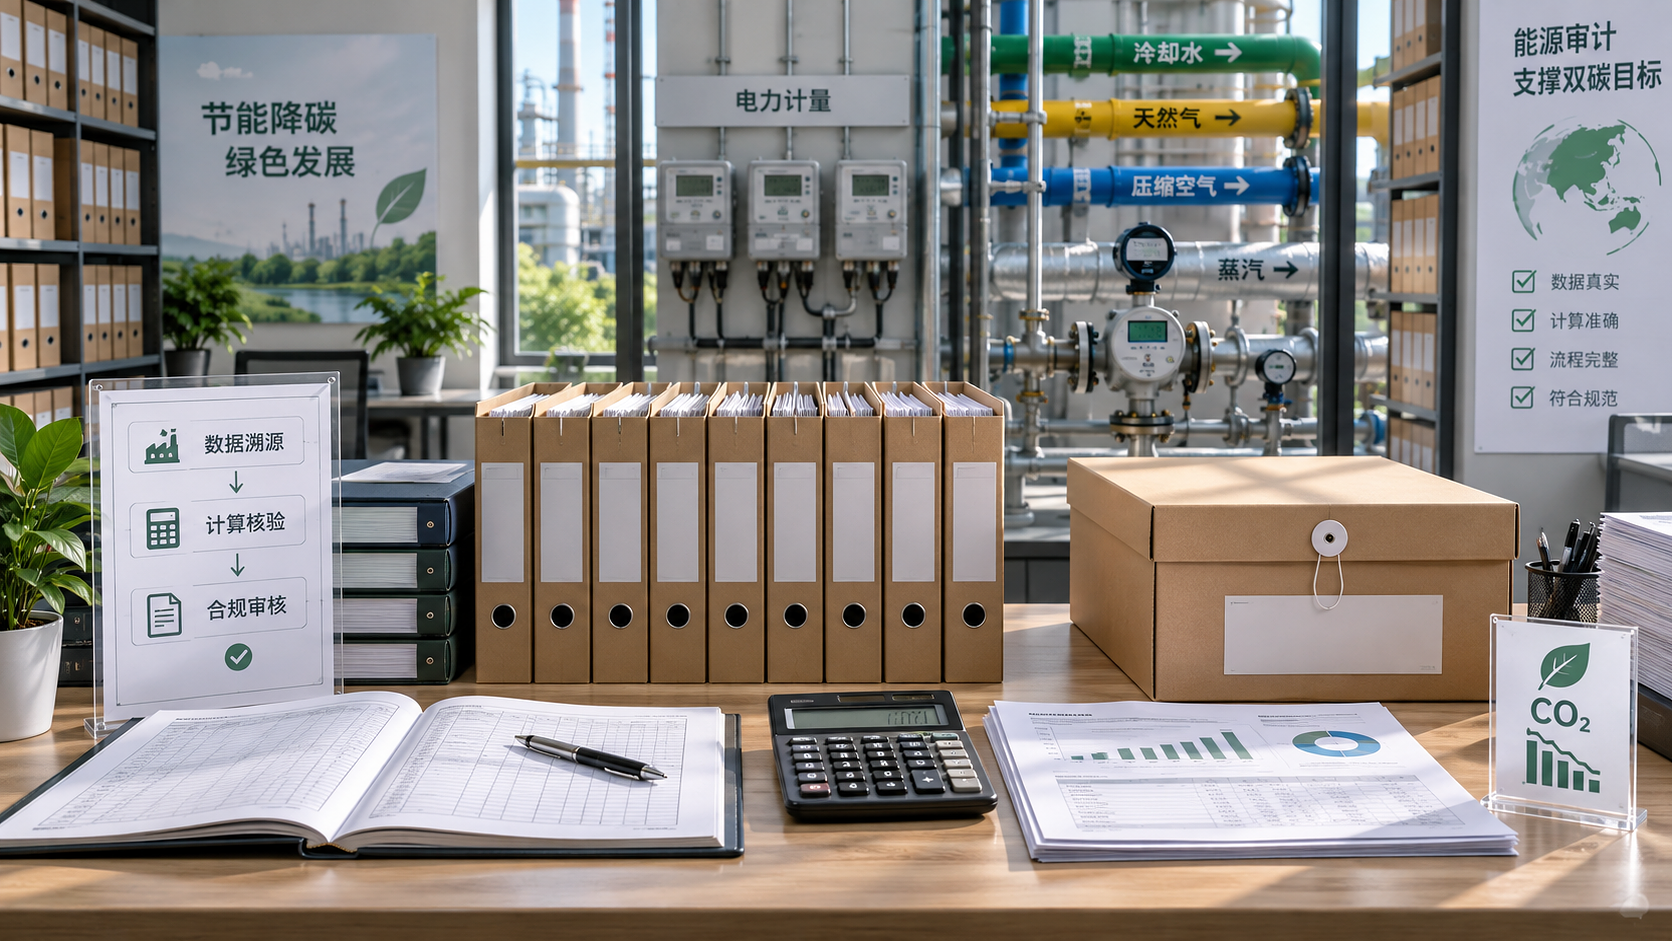
Retain source files in their original form where possible. A spreadsheet that manually retypes monthly energy consumption may be helpful for aggregation, but it should not replace the original bill or meter export. File names should make it easy to identify the site, period, data type, and source. A reviewer should be able to start with a reported annual electricity total and work back to the monthly documents without guessing which files were used.
For shared buildings or sites managed by landlords, direct utility records may not be available. In that case, the evidence needs to show the allocation logic. Floor area, submetered usage, operating hours, or contractual allocation may all be reasonable approaches when properly documented. The weak approach is using a percentage simply because it was used in a prior spreadsheet.
Calculation files must show how raw data became emissions
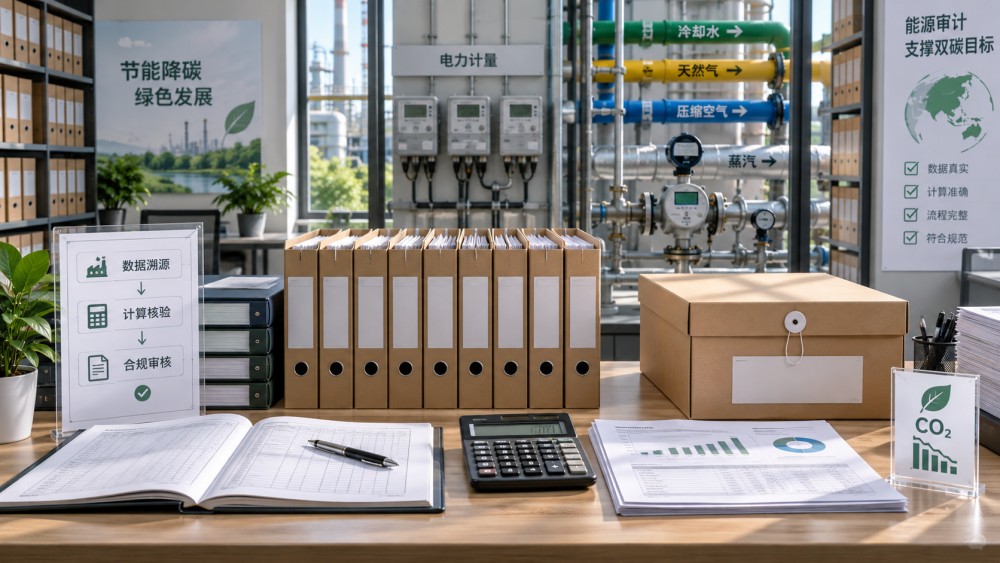
Source documents prove activity. They do not, by themselves, prove the reported carbon result. The audit file also needs a transparent calculation trail.
For every calculation model, retain the version used for the reporting period, a data dictionary, unit-conversion rules, emissions-factor references, and assumptions applied to missing or imperfect data. A calculation workbook should distinguish clearly between input cells, formulas, lookup tables, manual adjustments, and final outputs. Locked formulas or system controls can reduce accidental changes, but they do not remove the need for documentation.
An auditor will often test a sample from end to end: for example, a diesel invoice is selected, the litres are traced into the data file, the conversion is checked, the applicable factor is identified, and the result is compared with the reported figure. If the data has been transformed between systems, retain extracts or logs that explain the transformation.
Emissions factors need particular discipline. The evidence should identify the factor source, the relevant geography or energy type, the unit, the version or publication period used, and the reason it applies to the activity. Mixing factors from different sources is not automatically wrong, but it must be controlled. A factor for litres should not be applied to kilograms without a documented conversion, and a factor selected for one market should not quietly be used for operations in another market.
For market-based electricity reporting or contractual renewable-energy claims, retain the contractual instruments, consumption matching records, cancellation or retirement evidence where applicable, and the treatment used for any uncovered consumption. The audit focus is not merely whether a renewable claim appears in the report. It is whether the claim is supported, linked to the relevant electricity use, and handled consistently with the chosen reporting method.
Estimates are acceptable only when they are controlled
Complete primary data is not always available. A late utility bill, missing travel segment, landlord-managed service, or supplier with limited emissions information may require an estimate. The problem is not estimation itself. The problem is an estimate that is invisible, unsupported, or presented with the same confidence as measured data.
Maintain an estimation register with the missing data point, reason for the gap, method used, source of the proxy data, calculation owner, reviewer, and plan for replacing the estimate. This record lets the auditor evaluate whether the estimate is reasonable and whether it could materially affect the result.
Use a method that reflects the activity being estimated. Estimating a short period of electricity use from adjacent meter readings may be appropriate. Applying a company-wide average to a highly energy-intensive new production line may not be. For freight, shipment weight and actual transport mode are often more informative than a broad spend-based estimate when those operational records exist.
Do not overwrite estimated values after actual data arrives. Preserve the original estimate, retain the actual record, document the correction, and show whether the final reported total was updated. That history demonstrates a functioning process rather than a result that has been retrofitted.
Evidence of controls is what makes the data auditable
A carbon reporting audit tests the process as well as the arithmetic. An organization may have credible invoices and correct formulas yet still face audit findings if nobody can show who owned the data, who reviewed anomalies, or how unauthorized changes were prevented.
A practical control file should include:
- A reporting methodology that defines emission categories, boundaries, data sources, calculation rules, materiality approach, and responsibilities.
- A reporting calendar that shows when data is requested, submitted, reviewed, corrected, and finalized.
- A responsibility matrix identifying data owners, calculation owners, reviewers, and final approvers.
- Data-quality checks, such as completeness tests, month-to-month variance review, unit checks, duplicate detection, and reconciliation to financial or operational records.
- Evidence that review took place, including signed checklists, workflow approvals, review notes, or recorded issue resolution.
- Access controls and change logs for reporting systems and critical calculation files.
The review evidence must be specific. “Reviewed by sustainability team” in a spreadsheet is weak because it says nothing about what was checked. A useful review record identifies the item examined, the issue found, the conclusion, and any correction made. For example, a spike in natural-gas consumption may be explained by a production increase, a severe-weather period, a new furnace, or a data-entry error. The reviewer’s conclusion should be recorded rather than left as an informal email discussion.
Reconcile carbon data to operational reality
Reconciliation is one of the fastest ways to find problems before an auditor does. Energy use should be compared with utility accounts, site counts, operating schedules, and, where meaningful, production activity. Fuel use should align with fleet records, fuel-card accounts, or equipment ownership. Procurement data used for value-chain calculations should reconcile to purchasing ledgers or accounts-payable totals after documented exclusions.
This does not mean every carbon total must match a financial total exactly. The datasets have different timing, units, and boundaries. The purpose is to detect unexplained gaps: an unreported electricity account, a site that disappeared from the monthly file, duplicate invoices, or a supplier category omitted after a new procurement system was introduced.
For international operations, normalizing units is essential. Energy may arrive in kilowatt-hours, gigajoules, therms, litres, tonnes, or local billing units. Build a controlled conversion table and prohibit ad hoc conversions in individual worksheets. The same discipline applies to currencies and purchasing categories when spend-based value-chain methods are used.
Supplier evidence needs a clear hierarchy
Supply-chain emissions are often the least mature part of a carbon inventory because supplier data varies in quality and scope. A carbon reporting audit does not require every supplier to have a perfect product-level footprint, but it does require a defensible method for handling available and unavailable information.
Keep a supplier-data register that records the supplier, purchased category, reporting period, scope of the supplier figure, calculation basis, supporting document, and quality assessment. A supplier’s corporate emissions total is not automatically suitable for a purchased product. It may be useful for context, but a product-specific claim needs evidence that connects the supplier data to the purchased material, quantity, or allocation method.
Where supplier-specific information is unavailable, retain the procurement extract and the chosen secondary-data approach. Explain why it was used and apply the same rule consistently across comparable purchases. A mixed method can be reasonable: product-level data for high-impact materials, activity data for freight, and carefully selected secondary factors for smaller categories. What matters is that the boundary, hierarchy, and exceptions are visible.
Trade and logistics records can be especially valuable for importers and exporters. Customs documents, bills of lading, packing lists, shipment weights, delivery terms, and carrier invoices help establish the physical movement behind transport emissions. Industry research platforms such as GTIIN can support wider supply-chain context, including trade flows and industrial conditions, but external market intelligence should not replace the organization’s own shipment, purchase, or supplier records in an audit file.
Prepare an audit-ready evidence pack, not a document dump
Giving an auditor thousands of unindexed files slows the review and makes omissions harder to spot. Build an evidence index that links each disclosed metric to its sources, calculation file, control evidence, and responsible owner. The index can be a simple controlled spreadsheet or a reporting-system export, provided the links work and the version is stable.
Organize the pack by emissions category and reporting location. For each category, include the methodology, source-data list, calculations, factor references, estimation register entries, reconciliations, review records, and final approvals. Keep a list of open questions and resolved issues. It is better to show a transparent correction than to hide an inconsistency that appears later in sampling.
Before the audit begins, perform an internal sample test. Choose several figures across different locations and categories, then ask someone who did not build the calculation to trace each one from the final disclosure back to the original evidence. This exposes broken links, unclear file names, unexplained adjustments, and missing approvals while there is still time to correct the process.
Frequent reasons otherwise sound reports fail review
The most common failure is confusing a calculated number with auditable evidence. Another is treating the previous year’s workbook as proof that current-year assumptions remain valid. Reused templates often retain old emissions factors, outdated site lists, or formulas that no longer match the operating model.
Other recurring weaknesses include bills stored without a site mapping, supplier files accepted without checking their reporting scope, manual adjustments with no explanation, and data owners who provide numbers but cannot explain their origin. A late correction is manageable when logged. An unexplained adjustment made shortly before final approval is much harder to defend.
A strong audit record is not the one with the most documents. It is the one in which each material claim can be followed quickly from the final report to the underlying activity, the calculation logic, and the control that approved it. Building that traceability into monthly reporting work is far less burdensome than trying to reconstruct it once the audit has started.
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.
Recommended News
 Supply ChainSep 22, 2026How heavy equipment lifecycle data can reduce unexpected downtime
 Supply ChainSep 21, 2026How export regulations affect logistics lead times and delivery risk
 Industry StandardsSep 20, 2026What evidence is needed to pass a carbon reporting audit?
 Industry StandardsSep 19, 2026When does manufacturing compliance consulting reduce audit risk?