Using market intelligence to spot a global industrial slowdown
A global industrial slowdown becomes more credible when weakening demand appears across new orders, physical shipments, and factory operating conditions. A fall in freight rates or a weak manufacturing survey alone provides limited evidence. The stronger signal is a sequence: orders soften, backlogs shrink, deliveries become easier to obtain, and production loses momentum across several industrial regions.
Reading the global industrial outlook through market intelligence requires attention to that sequence, its geographic reach, and the reasons behind each movement. The practical question is whether demand weakness is spreading through connected supply chains or whether isolated disruptions are creating a misleading picture.
Look for transmission from orders to factory activity
Industrial demand travels through contracts, production schedules, inventory, and transport bookings before appearing in official output statistics. These stages move at different speeds. A machinery exporter can maintain shipments while completing an existing backlog, even as incoming orders weaken. Strong exports during that period describe earlier demand and can conceal deteriorating conditions ahead.
The relationship between new orders and backlogs therefore deserves particular attention. Falling new orders alongside a shrinking backlog suggests that future production coverage is thinning. If output remains stable, examine whether factories are completing old contracts, building finished inventory, or sustaining production because shutdowns would be costly.
Purchasing managers’ surveys offer an early view, but their construction matters. A diffusion index measures the breadth of reported improvement or deterioration; it does not directly measure the percentage change in production. A reading below the neutral threshold indicates that deterioration is more widespread among respondents. It does not establish the size of an industrial contraction.
Separate the survey components. Export orders reveal a different demand channel from domestic orders. Employment often adjusts after production schedules because skills are expensive to replace. Supplier delivery times require special care: faster deliveries can reflect weaker demand, restored capacity, or fewer transport disruptions. Their meaning changes with the accompanying order and inventory signals.
The same market signal can tell different stories
Useful market intelligence tests competing explanations before treating a movement as evidence of a global downturn. The following distinctions prevent several common errors.
These comparisons also reveal when evidence is being counted twice. Freight prices, port throughput, and customs exports can describe overlapping cargo flows. Agreement among them is useful, but it offers less independent confirmation than agreement between shipments, customer order intake, and factory utilization.
Separate weaker consumption from inventory correction
Destocking creates sharp industrial weakness even when final consumption changes relatively little. After accumulating excess materials, factories reduce purchases below current usage and draw down their warehouses. Upstream suppliers then experience a larger contraction than the downstream market.
This distinction changes the outlook. If final sales remain stable and excess inventory is steadily absorbed, purchasing can recover without a substantial improvement in consumption. If final sales are also falling, inventory clearance takes longer and the adjustment can spread into production cuts, employment, and investment.
Inventory composition provides the missing detail. Rising raw-material stocks can reflect precautionary purchases, minimum order quantities, or inputs arriving after production plans were reduced. Rising finished-goods stocks alongside slower shipments points more directly toward difficulty selling output. Work in progress requires a separate reading because missing components can leave partially completed equipment stranded on the factory floor.
Ratios need context as well. Inventory days can rise simply because sales have fallen, even when the physical stock balance is unchanged. Examine quantities and aging alongside the ratio. For engineered components, excess stock in an obsolete specification offers little protection against shortages in the specification still required.
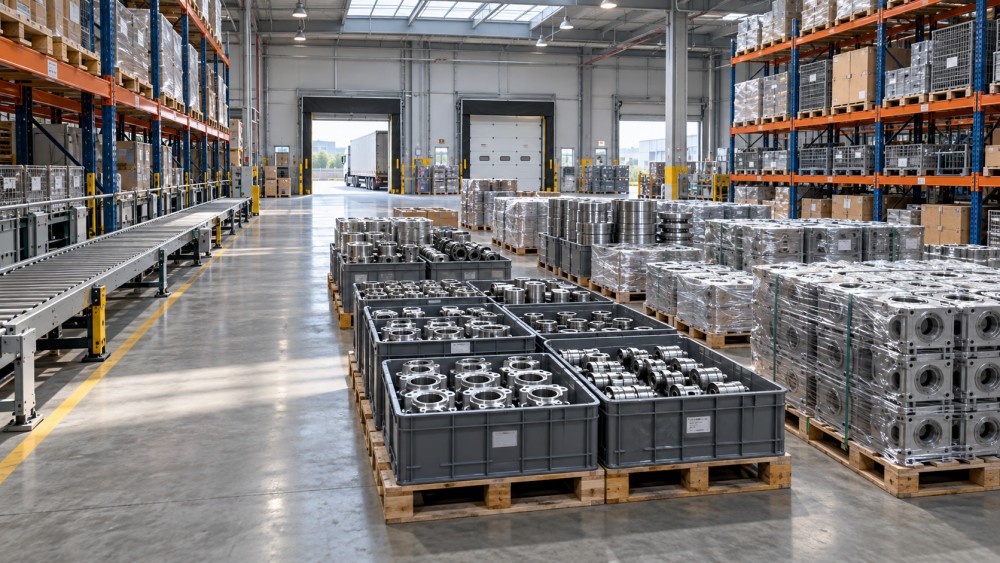
A useful diagnostic traces one product chain from final sales back through finished goods, production schedules, and material orders. If weakness intensifies upstream while downstream sales hold steady, inventory adjustment is a stronger explanation. If deterioration appears throughout the chain, the evidence supports a broader demand slowdown.
Establish whether weakness is becoming global
A downturn in one major manufacturing economy can affect global suppliers without constituting a synchronized global industrial contraction. Geographic breadth matters, but counting weak countries gives an incomplete answer. The relevant question is how much industrial demand those markets represent and whether weakness spans independent end markets.
Compare production origin with final demand. Several exporting economies can report weaker shipments because they serve the same destination market. That pattern shows a shared exposure, while leaving open whether other destinations are holding up. Similarly, assembly moving between countries can reduce one country’s exports and increase another’s without changing total demand for the finished product.
Sector breadth adds another test. Weak construction machinery demand and resilient electrical infrastructure orders can coexist because their investment cycles differ. Semiconductor shipments can be distorted by a product transition or an inventory correction. A stronger global slowdown signal appears when unrelated sectors lose orders and the weakness extends from discretionary capital equipment into recurring industrial inputs.
Weight the evidence against actual exposure. An industrial business with substantial demand from construction should give building activity and equipment utilization more influence than consumer-electronics shipments. A global dashboard remains useful, but its conclusions become actionable only when mapped to customer industries, destination markets, and supplier dependencies.
Build a timely picture without mixing incompatible data
Market intelligence becomes unreliable when series with different definitions and publication schedules are treated as directly comparable. Customs records, surveys, freight bookings, and company disclosures describe different stages of activity. Organize them by the economic period they measure, while retaining their publication dates to show what was knowable at each decision point.
Trade values require particular discipline. A decline in nominal steel exports could reflect lower prices despite stable tonnage. An increase in machinery export value could come from a few high-value deliveries while unit shipments weaken. Where quantity data are usable, compare value, volume, and unit value together. Where units are inconsistent, narrow the product category before drawing conclusions.
Seasonality can also overwhelm an early signal. Moving holidays, factory shutdowns, and differences in working days affect production and shipping calendars. Compare seasonally adjusted series where available, and examine several observations rather than extrapolating from a single month. Year-on-year comparisons also need scrutiny when the earlier period contained an exceptional disruption or surge.
Maintain a compact evidence record for each major indicator: source, coverage, reference period, release date, revision history, and the interpretation currently attached to it. This makes disagreements visible. If survey orders weaken while exports rise, the discrepancy becomes a question about timing, backlog, prices, or coverage instead of a reason to discard whichever series is inconvenient.
Confidence should increase when fresh evidence confirms an expected transmission. For example, weaker orders followed by declining production schedules provides stronger support than repeated commentary citing the original order decline. Conversely, stabilizing orders and improving downstream sales should reduce confidence in a worsening outlook, even if lagging output data remain weak.
Translate the diagnosis into reversible operating decisions
A slowdown signal does not justify cutting every purchase by the same proportion. The consequences depend on demand variability, replenishment time, supplier economics, and the cost of a stockout. Separate items whose purchasing can adjust quickly from those tied to lengthy qualification, specialized tooling, or infrequent production runs.
For standard materials with broad availability, weaker orders and shorter lead times support smaller replenishment commitments and closer review of stock targets. For custom castings, certified components, or specialized electronic parts, apparently abundant market capacity does not guarantee that an approved supplier can deliver the required specification on schedule.
Contract terms deserve attention before order volumes change. Minimum quantities, take-or-pay provisions, cancellation windows, and material already committed to production determine how much flexibility actually exists. Reducing a forecast without reconciling these obligations can shift excess inventory upstream and create disputes when demand returns.
Supplier stability can deteriorate during a downturn even as quoted lead times improve. Lower utilization spreads fixed costs over fewer units, while delayed customer payments strain cash flow. Requests for unusual deposits, repeated production rescheduling, and reduced material availability warrant investigation. Each signal needs operational confirmation; none alone proves financial distress.
Investment decisions benefit from explicit conditions. A capacity expansion based on persistent order growth should be reassessed if backlog coverage erodes across its intended end markets. A maintenance project addressing a reliability problem follows a different logic: weaker demand can create a practical shutdown window. Treating all capital spending as equally sensitive to the industrial cycle obscures those differences.
Define what would change the outlook
An industrial outlook should state the evidence required to strengthen or reverse its central judgment. A working view of broadening weakness becomes more convincing when new-order deterioration spreads, finished-goods inventories accumulate, and production cuts appear across unrelated markets. It weakens when final sales stabilize, excess stock clears, and fresh orders begin replenishing backlogs.
Use operating triggers tied to those observations. Shortening purchasing commitments can follow sustained deterioration in relevant orders and replenishment conditions. Releasing deferred capacity spending can require recovering demand across several customer segments, supported by actual orders rather than inquiries alone. The trigger should match the lead time and reversibility of the decision.
The next review then has a concrete purpose: determine whether demand weakness is spreading, inventory adjustment is nearing completion, or supply conditions have changed. That keeps market intelligence connected to decisions while allowing the global industrial outlook to evolve with the evidence.
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.
Recommended News
 Global SourcingOct 25, 2026How to find active suppliers in a trade intelligence platform dashboard
 Supply ChainOct 25, 2026Trade Tariffs Cause Whiplash at Port Milwaukee, Disrupting Cargo Flows
 Supply ChainOct 24, 2026How to use traceability to verify supply chain sustainability claims
 Market TrendsOct 24, 2026FedEx Report: AI Drives Asia-Pacific Chip and Digital Infrastructure Supply Chain Demand