ESG Reporting Checklist: Key Metrics That Reduce Compliance Risk
A strong ESG reporting checklist has become a practical control framework, not just a disclosure exercise. For organizations managing global sourcing, industrial procurement, and cross-border supply chains, ESG reporting helps translate broad sustainability expectations into trackable metrics, clearer accountability, and lower compliance risk.
That matters more now because reporting demands are expanding from investors to regulators, lenders, major buyers, and customs-linked policy regimes. In many sectors, weak ESG reporting no longer creates only a reputational gap; it can disrupt supplier approval, contract renewal, market access, and resilience planning.
Why ESG reporting now sits at the center of compliance control
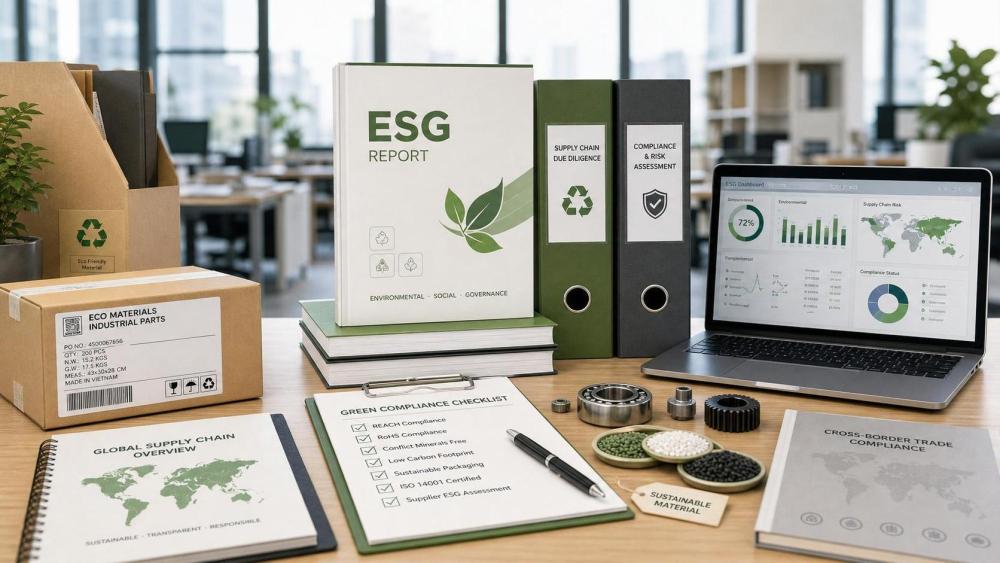
The pressure around ESG reporting comes from several directions at once. Climate disclosure rules are tightening. Human rights due diligence is moving deeper into supply chains. Trade-facing businesses also face carbon, traceability, and sourcing scrutiny across multiple jurisdictions.
In practice, a checklist works because it narrows attention to material evidence. It helps separate what must be measured from what is simply nice to mention. That distinction reduces the risk of inconsistent claims, missing records, and supplier data gaps.
For a platform like GTIIN, which analyzes industrial value chains, export trends, and supply chain resilience, this shift is especially relevant. ESG reporting is increasingly tied to sourcing decisions, freight exposure, regional compliance changes, and the operational realities behind global trade data.
What an ESG reporting checklist should really capture
A useful checklist is not a long catalog of generic indicators. It should focus on metrics that connect directly to legal exposure, buyer expectations, financing reviews, and operational continuity.
Usually, the most reliable structure covers three layers: internal operations, supplier network evidence, and governance controls. Together, these show whether ESG reporting reflects actual performance or only policy language.
Environmental metrics
Environmental disclosure tends to attract the most formal scrutiny. Yet the goal is not to report everything. The goal is to report the variables that affect emissions, resource intensity, and product-linked compliance obligations.
- Scope 1 and Scope 2 emissions, with clear calculation boundaries and reporting periods
- Material Scope 3 categories, especially purchased goods, transportation, and upstream processing
- Energy consumption by source, including renewable share and energy intensity trends
- Water withdrawal and discharge in water-stressed or regulated operating regions
- Waste generation, hazardous waste handling, and recovery or recycling rates
- Product or shipment data linked to carbon border mechanisms or product environmental declarations
These metrics become more valuable when tied to production volume, supplier category, and trade lane exposure. Absolute numbers alone rarely explain compliance risk.
Social and labor metrics
Social indicators often create the sharpest hidden risk because documentation is uneven across regions. ESG reporting should show how labor standards are governed, monitored, and corrected in practice.
- Workplace injury rates, near-miss reporting, and lost-time incident trends
- Employee turnover, training hours, and critical workforce retention indicators
- Supplier audit coverage for labor rights, wages, working hours, and grievance systems
- Corrective action closure rates after audits or reported violations
- Conflict minerals, forced labor, or traceability declarations where sector rules require them
This is where ESG reporting often fails. Companies publish codes of conduct, but they cannot show audit depth, remediation timing, or exception management. That gap invites compliance challenge.
Governance metrics
Governance data determines whether disclosures can be trusted. It also indicates whether risk signals are escalated early enough to influence sourcing, contracting, and executive decisions.
Where compliance risk usually appears first
Most ESG reporting problems do not begin in the final report. They begin earlier, in boundary confusion, fragmented supplier data, or weak ownership of evidence.
Cross-border industrial networks are especially exposed. One business may source metals from one region, components from another, and final assembly from a third. Each layer can sit under different disclosure norms, labor expectations, and environmental baselines.
This is why checklist design should reflect operating reality. GTIIN’s supply chain mapping perspective is useful here because trade intelligence can reveal where ESG reporting needs deeper validation: high-risk origins, long transport chains, concentrated supplier clusters, and regions facing regulatory transition.
- Mismatch between legal entity boundaries and operational boundaries
- Supplier self-declarations without audit or transactional evidence
- Emissions calculations that ignore logistics-heavy trade models
- Policy claims not supported by training, incident logs, or remediation records
- Different regional data formats that weaken comparability across sites
How to apply the checklist in real business settings
The best use of ESG reporting is not annual publication alone. It is ongoing decision support. A checklist becomes more effective when embedded into supplier onboarding, sourcing reviews, capital planning, and contract monitoring.
Supplier screening and segmentation
Not every supplier needs identical scrutiny. Higher-risk categories usually include carbon-intensive materials, labor-sensitive production, and jurisdictions with weak enforcement. ESG reporting should therefore be tiered by exposure, not treated as a flat survey process.
Cross-border disclosure readiness
If goods move into regions with stricter climate or due diligence rules, ESG reporting should capture shipment-linked data, origin traceability, and evidence retention. This matters for customs, customer questionnaires, lender reviews, and contract representations.
Operational resilience analysis
A compliance-focused checklist also supports resilience analysis. Energy volatility, water stress, labor disruption, and transport exposure all have ESG dimensions. Reporting that connects these metrics to continuity planning becomes far more useful than a stand-alone sustainability narrative.
A practical way to judge reporting quality
High-quality ESG reporting is usually recognizable by a few consistent traits. The data is scoped clearly. Metrics are linked to business activities. Exceptions are disclosed rather than hidden. And supplier-related claims can be tested against documentation.
A useful review process can follow this sequence:
- Identify which ESG topics are financially or operationally material
- Map each material topic to a measurable metric and data owner
- Test whether supplier evidence is current, comparable, and auditable
- Check whether trade flows, logistics, and sourcing regions change risk exposure
- Prioritize gaps that could affect disclosure accuracy or market access
This approach keeps ESG reporting grounded in control quality. It also avoids the common mistake of over-reporting immaterial items while missing the metrics that regulators and counterparties actually examine.
What to do next with an ESG reporting checklist
The next step is rarely to add more metrics. It is to improve relevance, ownership, and evidence. Start by reviewing where the business faces the greatest trade, sourcing, and disclosure pressure. Then align ESG reporting with those exact pressure points.
For organizations operating across industrial sectors and international corridors, external intelligence also matters. Monitoring regulatory shifts, export patterns, supplier-region risk, and sector-specific benchmarks can sharpen the checklist over time.
In that sense, ESG reporting works best when it is treated as part of a broader market and supply chain intelligence process. A focused checklist does not solve every compliance issue, but it does create a clearer basis for action, comparison, and better-informed cross-border decisions.
Have questions about this sector analysis, or seeking best practices specific to your niche? Drop us a line below and let the senior consultants at GTIIN assist you.
“We respect your privacy. Your information is strictly confidential.”
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.
Recommended News
 Supply ChainNov 08, 2026He Lifeng Holds Trade Talks With Bessent and Greer
 Market TrendsNov 08, 2026How to use industrial commodity market analysis to forecast costs
 Supply ChainNov 07, 2026EU Opens Safeguard Investigation into PET Resin Imports
 Industry StandardsNov 07, 2026Which ISO quality management standard can a company be certified to?